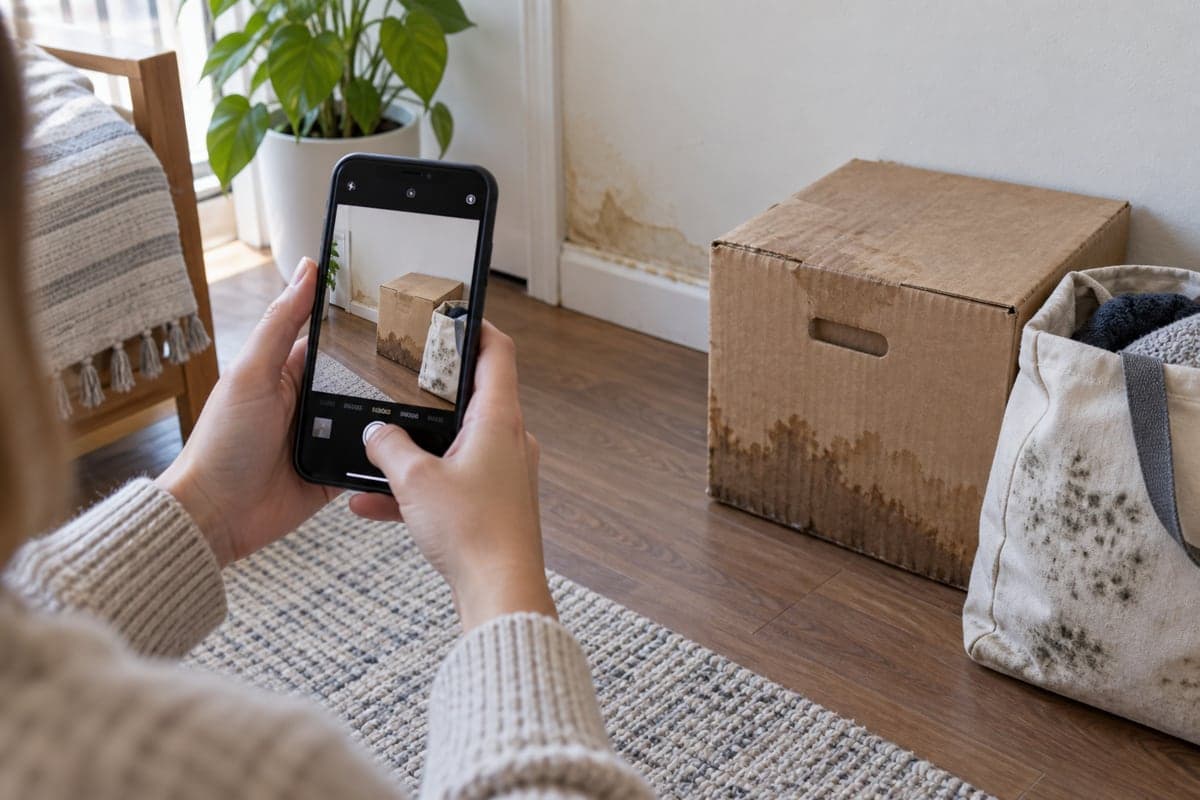
If a home inspection turns up mold, or signs of it such as water stains or a musty smell, nothing happens automatically. The deal isn't canceled, and no law requires a specific fix. What happens next is up to you and the seller, within the terms of your purchase contract. If the contract depends on a satisfactory inspection, the Consumer Financial Protection Bureau explains that you can cancel without penalty if you aren't satisfied with the results, or negotiate with the seller about who makes or pays for repairs. The key questions are how much mold there is, what moisture problem caused it, and whether that problem can be fixed for a price you can accept. Move quickly, because inspection contingencies have deadlines.
A standard home inspection is a first screen, not a mold investigation. Use the report to decide whether you need more information, and then decide whether to negotiate, ask for repairs, or walk away.
What a Home Inspector Can and Can't Tell You
Home inspectors look for visible conditions. Most aren't required to determine whether mold is present:
- The InterNACHI standards of practice say an inspector isn't required to determine "the presence of mold, mildew or fungus," or the existence of environmental hazards.
- ASHI's 2026 standard of practice likewise lists mold, fungus, and environmental hazards among the things inspectors aren't required to determine.
- In Texas, state rules for real estate inspectors don't require them to report on mold or mildew. The state's mold licensing agency says a real estate inspector must hold a mold assessment license to collect mold samples.
So a report that says "possible mold" or "recommend evaluation by a qualified professional" usually means the inspector saw something worth a closer look, not that a lab confirmed anything. It also means a report with no mention of mold doesn't guarantee there's none behind walls, under flooring, or in the attic.
Step One: Check Your Contingency Deadline
Before anything else, find the inspection contingency in your contract and note the deadline. Your options for canceling or negotiating usually depend on acting within that window. If you need more time for a specialist to look, ask your real estate agent or attorney how to request an extension in writing before the deadline passes.
Contract terms vary widely, and this isn't legal advice. Your agent or a real estate attorney can tell you what your contract allows.
Step Two: Figure Out How Serious It Is
Mold in a house is common. What matters is the size of the problem and its cause. Work through these questions with your inspector or a specialist:
- Where is it? Surface growth on a bathroom ceiling from poor ventilation is very different from mold in wall cavities, crawl spaces, attics, or ductwork.
- How big is it? The EPA says most people can clean up an area smaller than about 10 square feet, roughly a 3-by-3-foot patch. Larger areas usually call for a professional.
- What caused it? A roof leak, plumbing leak, foundation seepage, poor drainage, condensation, or high humidity. The EPA warns that if you clean up mold but don't fix the water problem, "most likely, the mold problem will come back."
- Is the moisture still active? Ask whether the inspector took moisture meter readings.
- What materials are affected? Drywall, insulation, ceiling tiles, and carpet with mold often need to be removed and replaced rather than cleaned.
Is a mold test worth it? Often not, if the growth is visible. The EPA says sampling is usually unnecessary when mold can be seen, and that there are no federal standards for airborne mold. The CDC does not recommend mold testing, and NIOSH says a thorough visual inspection or a musty odor is more reliable than air sampling. An independent assessment is more useful when you need to know how far hidden damage extends, where the moisture is coming from, and what a fix should include. See who to call for a mold inspection and how much a mold inspection costs.
Keep the assessor and the remediator separate. A company that sells mold removal has a reason to find more mold. Some states require the separation. Texas, New York, and Florida bar the same licensee from both assessing and remediating the same project, and Florida extends that to structures assessed within the past 12 months.
Your Options as a Buyer
Once you know the scope, you generally have these choices:
- Ask the seller to fix it before closing. Ask for the moisture source to be repaired and the mold remediated by qualified contractors, with documentation (see the next section).
- Negotiate the price or who pays. If you'd rather control the repair yourself, get written quotes first so you know what you're negotiating over. Our guide to how much mold removal costs explains what drives the price. The CFPB notes that depending on your contract and local market, sellers may or may not agree to pay for repairs.
- Cancel the purchase. If your contract has an inspection contingency and you act within its terms, you can walk away without penalty.
- Accept the house as it is. This can be reasonable for small, well-understood problems with a known and fixable cause. Budget for the repair and plan to fix the moisture source soon after you move in.
If the Seller Fixes It Before Closing
A seller's repair is only as good as the work behind it. Ask for:
- Proof the moisture source was repaired, such as invoices from a plumber, roofer, or drainage contractor.
- A written scope and invoice from the remediation contractor showing what was removed, cleaned, and dried.
- Licensed contractors where your state requires them. Texas, Florida, New York, and Louisiana have mold licensing programs, with different thresholds. Texas requires a license for projects of 25 contiguous square feet or more, while Florida and New York use a 10-square-foot line.
- Before and after photos, including opened walls if materials were removed.
- An independent post-remediation check, ideally by someone other than the company that did the work.
The EPA's remediation guidance lists signs the job is finished: the water or moisture problem is completely fixed, visible mold and moldy odors are gone, and a revisit shows no signs of water damage or new growth. If air sampling was done, indoor mold should be similar to what's found outdoors.
In Texas, a licensed remediation project ends with a Certificate of Mold Damage Remediation that states whether the underlying cause was corrected. Sellers must give buyers copies of any such certificates they received for the property in the past five years. The state also says the certificate prevents an insurer from making an underwriting decision based on the previous mold damage.
For what a realistic schedule looks like, including drying and rebuilding, see how long mold remediation takes. If quotes use different terms for the same work, mold remediation vs. removal vs. abatement explains the difference.
Disclosure, FHA Loans, and Insurance
Seller disclosure. We found no federal requirement for sellers to disclose mold. That's different from lead-based paint, where the EPA's disclosure rule requires sellers of most pre-1978 homes to disclose known lead hazards. State disclosure forms vary. The Texas seller's disclosure notice asks about previous water damage and flooding, and California's disclosure statement asks about known environmental hazards. Ask the seller directly about past leaks, water damage, insurance claims, and any previous mold work, and get the answers in writing.
FHA loans. An FHA appraisal is not an inspection. HUD's buyer notice says "FHA does not perform home inspections" and suggests asking your inspector whether other tests, such as mold, are relevant. Under HUD's handbook, if an appraiser sees evidence of a deficient condition, such as a water-stained ceiling or a smell of mold, the appraiser must report it and may make the appraisal subject to inspection and repairs.
Insurance. The Insurance Information Institute says mold is generally treated as a maintenance issue that standard homeowners policies don't cover. Removal may be covered when the mold results from a covered event, such as a burst pipe. Ask an insurance agent how the known mold or water history could affect your policy before you close.
When Walking Away May Make Sense
These situations deserve extra caution:
- The moisture source is unclear, or involves the foundation, grading, roof structure, or a chronic drainage problem.
- Mold is widespread, in multiple rooms, or spread through the heating and cooling system.
- The seller won't allow further evaluation or won't provide documentation of past repairs.
- Quotes for repair exceed what you can afford or negotiate.
- Someone in your household has asthma, a mold allergy, chronic lung disease, or a weakened immune system. The CDC says these people can have more severe reactions or lung infections from mold.
Don't let color drive the decision. The CDC says all molds should be treated the same with respect to potential health risks and removal, and NIOSH notes that color doesn't necessarily show whether a mold is more or less dangerous. For more, see what kind of mold is dangerous in a house.
Frequently Asked Questions
Is mold a deal-breaker when buying a house?
Not necessarily. Small areas with a clear, fixable cause are often handled through repairs or negotiation. Extensive mold, hidden damage, or a moisture problem that's hard to fix is a stronger reason to reconsider.
Does a home inspector test for mold?
A standard inspection usually doesn't include mold testing. Inspection standards say inspectors aren't required to determine whether mold is present. Some inspectors offer mold assessment as a separate service, and some states, such as Texas, require a mold license to collect samples.
Should I pay for a mold test before closing?
Only if it answers a real question. When mold is visible, the EPA says sampling is usually unnecessary. An assessment focused on finding the moisture source and the extent of damage is usually more useful than lab results alone.
Does the seller have to disclose mold?
It depends on your state and the disclosure form it uses. We found no federal mold disclosure rule for home sales. Ask the seller in writing about any known leaks, water damage, and past mold work.
Can you get an FHA loan on a house with mold?
Possibly. If the appraiser sees signs of a deficient condition, such as water stains or a mold smell, they must report it and may require inspection and repairs before the loan can proceed.
Who pays to fix mold found during an inspection?
It's negotiable. The seller may fix it, lower the price, or refuse, and your contract terms and local market affect what's realistic. Get written quotes before you negotiate.
Sources
- CFPB: Schedule a home inspection — inspection contingencies, canceling, and negotiating repairs.
- InterNACHI standards of practice, ASHI 2026 standard of practice, and 22 Tex. Admin. Code § 535.227 — mold outside the scope of standard home inspections.
- EPA: A Brief Guide to Mold, Moisture and Your Home — the 10-square-foot guideline, fixing the water problem, and sampling.
- EPA: Mold Remediation in Schools and Commercial Buildings — how to tell when remediation is finished.
- CDC: Mold, Facts About *Stachybotrys chartarum*, and NIOSH: Mold testing and remediation — testing, higher-risk groups, color, and treating all molds the same.
- TDLR mold FAQ and Texas Consumer Mold Information Sheet — sampling licenses, conflict-of-interest rules, certificates, and disclosure to buyers.
- New York Labor Law § 936 and Florida Statutes § 468.8419 — separating assessment from remediation.
- Louisiana State Licensing Board for Contractors — mold remediation licensing.
- EPA: Lead-based paint disclosure rule and TREC seller's disclosure notice — federal and state disclosure requirements.
- HUD: For Your Protection, Get a Home Inspection and HUD Handbook 4000.1 — FHA appraisals and mold.
- Insurance Information Institute: Protecting your home from mold — mold and homeowners coverage.