Renters insurance may cover mold-damaged belongings when the mold results from an event your policy covers, such as an accidental burst pipe. It usually does not cover mold caused by ongoing dampness, gradual leaks, or neglect. Exclusions, endorsements, deductibles, and coverage limits still apply, so a covered water event does not automatically mean every mold-related expense will be paid.
This guide concerns U.S. renters policies. Your contract and applicable state law control. When you contact the insurer, describe the water event, affected belongings, and timeline rather than assuming all parts of the loss have the same coverage.
Start With What Caused the Mold
The Texas Department of Insurance's water and mold guidance distinguishes sudden accidental water damage from gradual leaks. It also distinguishes damage to an item from additional mold cleanup and testing. Although this is a state regulator's guidance, those are useful questions to raise with an insurer anywhere.
Consider these examples as starting points, not claim decisions:
- A supply pipe bursts and wets your rug: The water loss and resulting mold damage may qualify, subject to the policy's terms and your actions to limit further damage.
- A closet stays damp for months: Humidity-related mold is generally a maintenance or gradual-damage issue rather than a covered sudden loss.
- A slow leak was present before you moved in: Ask the landlord to address the source and ask the insurer about the timing and exclusions. A new policy does not retroactively insure old damage.
- Outdoor floodwater enters the unit: Standard renters insurance generally excludes flood damage; a separate flood policy is a different contract with its own limits and exclusions.
- A sewer backs up: Do not assume ordinary water-damage coverage applies. Ask whether you have a water-backup endorsement and whether its wording covers resulting mold.
Progressive's mold coverage explanation illustrates how covered perils and neglect can lead to different outcomes. A landlord's or contractor's verbal assurance is not a coverage determination from your insurer.
Separate Your Belongings From the Building
Renters insurance typically protects your personal property, such as clothing, a sofa, and electronics, against covered losses. It does not insure the landlord's building as your dwelling. The NAIC's explanation of renters policies makes this distinction.
For a mold claim, keep separate records for:
- Your damaged belongings and the cost to clean, repair, or replace them.
- The landlord's walls, built-in cabinets, fixed flooring, and other building materials.
- Temporary living expenses if you cannot remain in the rental.
- Testing, assessment, and remediation charges, including who authorized them.
An adjuster may consider cleaning an item before replacing it. Ask what documentation and approval are needed before hiring a contents-restoration company.
If you are comparing a contractor's scope, our mold removal cost guide explains how access, drying, demolition, and rebuilding affect the bill. Those project costs are not a statement of what your renters policy will reimburse.
Will Insurance Pay for a Hotel or Mold Inspection?
Temporary accommodation may be covered when an insured loss makes the rental uninhabitable. Loss-of-use or additional-living-expense coverage generally concerns necessary extra costs above your normal spending, within the policy's time and dollar limits. The Texas insurance department's renters guide describes this coverage separately from personal property.
Ask the adjuster how eligibility is determined, what lodging budget applies, whether approval is needed, and which receipts to save. Do not assume that choosing to leave because of a musty smell automatically triggers hotel reimbursement. If immediate conditions are unsafe, seek a safe place and contact the insurer promptly rather than remaining solely to await a coverage decision.
An inspection or broad mold-removal bill is not automatically covered. Progressive notes that renters policies typically do not pay for a mold inspection. Ask who is responsible for arranging an assessment and whether an approved claim includes any testing expenses. Our guide to who to call for a mold inspection explains the different roles of an assessor and a remediation contractor.
Read the Limits Before Estimating a Payout
Get the full policy, including endorsements, rather than relying only on a declarations page. Search for terms such as “mold,” “fungi,” “wet or dry rot,” “water damage,” “seepage,” “loss of use,” and “duties after loss.” Ask the adjuster to identify the clauses that apply to your situation.
Check the property deductible, any special mold limit, and whether cleaning, testing, and accommodation share a limit or have separate limits. A high total personal-property limit does not override a narrower exclusion or sublimit.
Also check whether belongings are settled at actual cash value or replacement cost. NAIC's renters insurance guidance explains that actual cash value accounts for depreciation, while replacement coverage follows different settlement terms. Ask whether replacement receipts are required to recover the full eligible amount.
Document and Report the Damage
Report the problem to both your landlord and insurer promptly. For the landlord communication and practical next steps, see what to do about mold in your apartment.
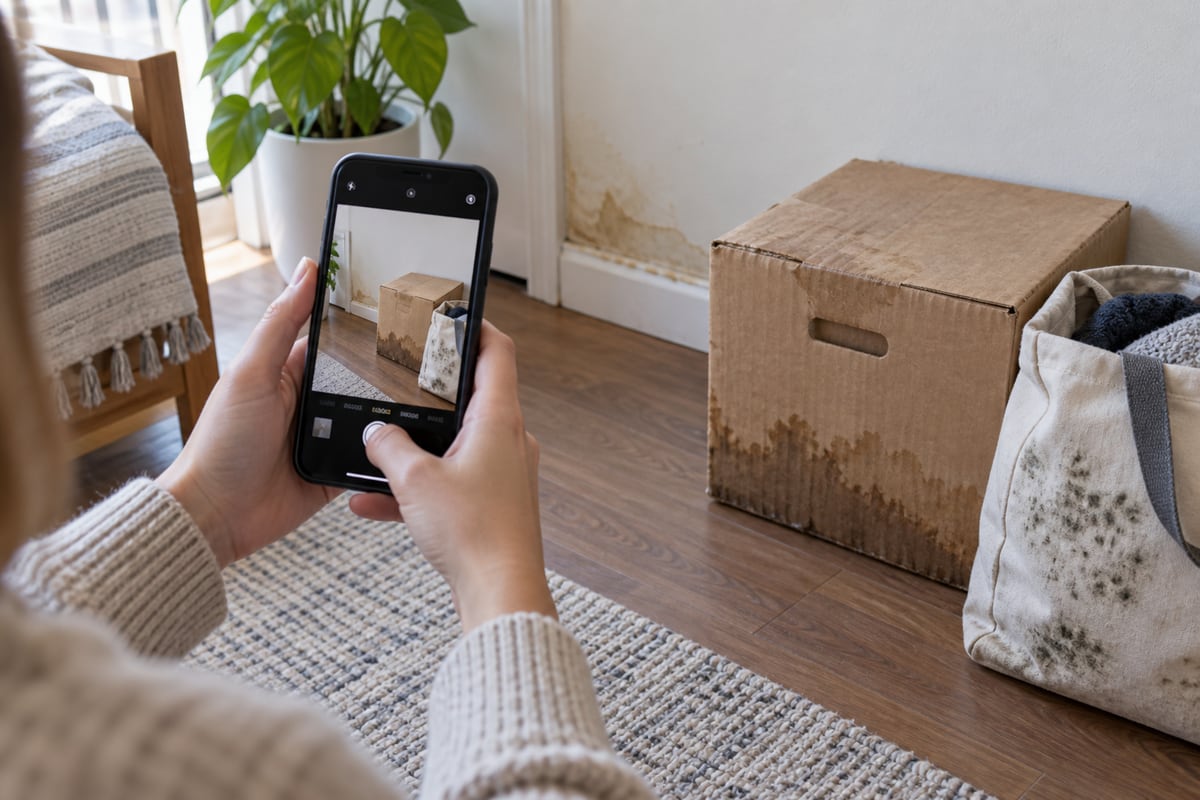
- Record when you discovered it. Save photos of the water source, affected room, and individual belongings. Preserve earlier repair requests and replies.
- Describe the facts accurately. Give the discovery date, known leak history, and areas affected. Say when you do not know the cause.
- Limit further damage safely. Report or stop the leak if safe, protect unaffected belongings, and ask about emergency drying. Do not undertake building demolition yourself.
- Make an itemized inventory. Include descriptions, approximate purchase dates, receipts where available, and photos. Keep damaged-item evidence until the adjuster gives instructions, while avoiding unsafe storage or exposure.
- Ask before authorizing major work. Clarify who contracts for the job and what the insurer requires before disposal, permanent repairs, testing, or restoration.
- Keep a claim log. Record the claim number, contacts, instructions, quotes, and receipts. Request important decisions in writing.
These steps build on TDI's claim documentation guidance. They help an adjuster evaluate the claim but do not guarantee payment.
If the Landlord Is Responsible or the Claim Is Denied
Insurance coverage and landlord responsibility are separate questions. An exclusion in your renters policy does not settle who must repair the building, and the landlord's building insurance does not automatically cover your belongings. Responsibility can depend on the cause, notice, lease, and local law.
For an unresolved repair issue, contact local housing or code enforcement, a tenant-assistance organization, or legal aid. Get advice specific to your location before withholding rent, paying for major repairs yourself, or trying to end the lease.
For an insurance denial, request the reason and policy language in writing. Compare the decision with the evidence and any endorsements, then ask about the insurer's review process. Your state insurance department can explain complaint options; the NAIC directory of insurance departments is a starting point.
Frequently Asked Questions
Does renters insurance cover black mold differently?
Do not assume so. The cause of loss and policy wording determine coverage; the color of a patch does not itself establish a covered peril or special payout.
Can I buy coverage after finding mold?
A new policy or endorsement does not retroactively cover an already existing loss. Disclose the situation accurately and ask about future coverage options after the underlying problem is addressed.
Will flood insurance cover mold on my belongings?
Do not assume that it will. Renters can obtain separate contents flood coverage, but it has its own exclusions and conditions. FEMA's NFIP recovery guidance emphasizes prompt drying and restrictions on mold damage. Ask the flood insurer how the wording applies to your loss.
Is all mold removal the landlord's responsibility?
There is no single nationwide answer for every rental and cause. Request a written repair plan and keep the building work separate from your personal-property claim. Local tenant advice can help resolve responsibility disputes.